
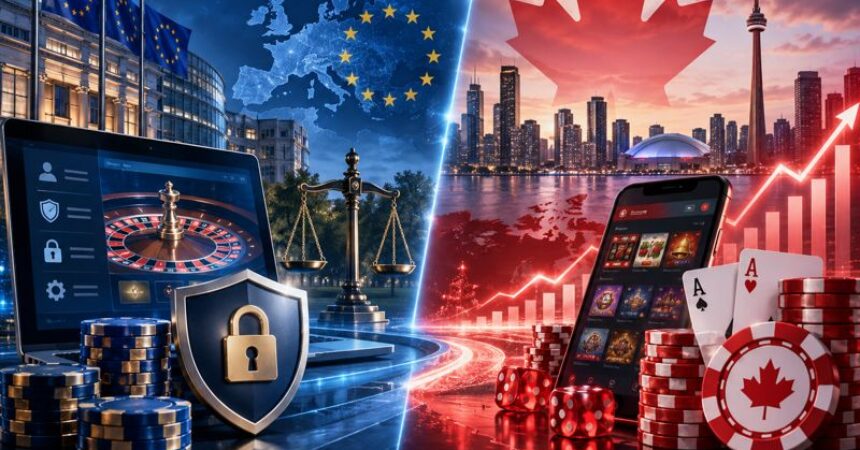
Europe’s well-established iGaming market has been expanding for many years, and while regulations may be fragmented and approaches for regulation differ between otherwise similar countries, there’s no question that the continent has lots of experience with managing online casino operations. Canada’s relatively recent legalization of iGaming is quite distinct from its European equivalent, with regulations focusing on growth and ongoing debate shaping the direction the industry will take going forward. As diverging paths to regulating a hotly discussed segment, they’re worth examining.
Canada’s Emphasis on Competition
Prior to giving the greenlight for locally licensed and regulated iGaming, Canada had a stance that was similar to many other parts of the world, in that running casino sites domestically was banned, but a large grey market existed as residents placed bets on overseas platforms. The legitimization of iGaming on Canadian soil made sense as a way to drum up tax revenues as much as anything else, and while the only province to welcome commercial operators so far is Ontario, it’s initial success is making wider uptake extremely likely.
Key players in Canada’s trusted live casino niche have been effectively encouraged by regulators to grow rapidly, with relatively lenient rules regarding the marketing of their products partly fuelled by the desire to pull as many people away from the aforementioned grey market as possible. In turn, the top gambling brands have enjoy extensive exposure in the media and rapid brand recognition proliferation, enabling them to spread the message and spur growth in revenues as well as tax takings.
Europe’s Focus on Player Protection

Canada’s rush for iGaming growth contrasts with the increase of regulatory pressure in many parts of Europe, with the authorities intending to provide better protection for players who are at the problematic end of the spectrum in terms of their gambling habits. In Germany, for example, imposing very modest maximum wager caps on slots games and introducing limits on deposits across the board has seen the industry put under more pressure, leading some operators to feel that the market is no longer worth serving.
Ideally a happy medium between the two approaches will be found, and a combination of Europe’s experience and Canada’s commercial-first growth strategy may pan out best for operators and customers alike. There’s no question that player protections and responsible gambling tools are important, but if they create a situation in which iGaming operators stop serving specific European markets, then the grey market will only step in once again to fill the gap.
Similarly, Canada’s relatively lenient approach to regulating iGaming advertising may prove to be a mistake if it leads to growing anti-gambling sentiments among certain demographics and groups. Choosing to impose additional restrictions, more aligned with how this is managed in Europe, while still giving brands a chance to showcase their offerings to the right audiences, should be a priority.
There’s definitely a convergence of iGaming regulation in Canada and Europe, and one that’s increasing over time. Long-term trajectories for the industry in both locations should play out positively in terms of growth, providing that regulatory sticking points are cleared up.